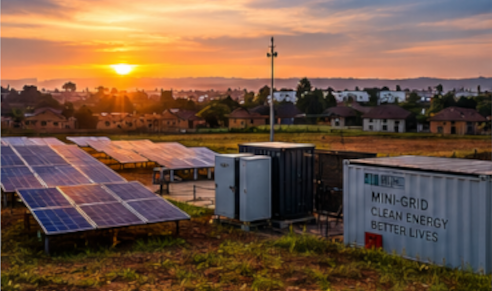
Over the past year, Nigeria’s distributed-energy sector has absorbed an unusual concentration of institutional capital in a short window. A combined $83.2 million from IFC and Norfund landed across five mini-grid developers. A further $188 million Green Finance Facility was launched to fund forty interconnected mini-grid deployments across twelve project lots. One operator alone closed a $103 million Series D built explicitly around a 500-site expansion plan. This is not scattered, opportunistic capital arriving in the ordinary course of a growing sector. It is a wave — development finance institutions, blended-finance vehicles, and impact investors converging on the same thesis inside the same eighteen-month window, each running its own diligence process, each reaching the same conclusion from a different angle.
Every organization inside that wave did the hard part already. Each one built a case strong enough to survive a due-diligence process explicitly designed to say no more often than yes. Financial models were stress-tested. Regulatory exposure was mapped. Governance structures were examined by people whose job is to find the reason not to fund something. They closed anyway.
This is happening now, in a specific and identifiable ecosystem — Nigeria’s mini-grid and off-grid electrification sector, operating inside a regulatory environment that itself changed mid-cycle, with new mini-grid classifications and expanded capacity thresholds altering what “compliant” even means for some of these developers between the term sheet and the first disbursement. But the pattern is not confined to Nigeria, and it is not confined to energy. It shows up anywhere an organization has just persuaded a sophisticated institutional funder to commit serious capital, and the world outside that funder is beginning to ask its own questions in parallel.
The same pattern compounds, rather than simply repeats, once an organization’s footprint crosses a border. A distributed energy utility operating across Nigeria and Madagascar, or an off-grid provider serving twelve countries under a single continental mandate, is not managing one institutional case read by one regulator. It is managing a single underlying narrative that has to survive being read by multiple national regulators simultaneously, each applying a different licensing framework, each with a different tolerance for the same disclosed risk, and each capable of treating a governance gap that one jurisdiction shrugs off as a serious compliance failure in another. A document written to satisfy Nigeria’s regulatory posture on foreign ownership or local content does not automatically satisfy the equivalent requirement three borders away, and an organization that has not deliberately built its institutional case to be legible across jurisdictions is, in effect, running several different unstated versions of the same story and hoping none of its readers compare notes. Increasingly, they do.
The assumption that tends to follow a close is a natural one, and it is rarely spoken aloud because it does not need to be — it is simply how attention reallocates. The institutional case has done its job. The document, the deck, the data room that got the raise across the line can be filed, and focus returns to execution: building sites, connecting households, hitting the operational milestones the term sheet is now measuring against a calendar.
This is precisely where the assumption breaks, and it breaks quietly, because nothing about it looks like a mistake at the time. A DFI-backed raise does not conclude an organization’s relationship with institutional scrutiny. It inaugurates one, on different terms than existed before the money arrived. Covenant reporting continues on a fixed schedule, often quarterly, often reviewed by people who were not part of the original investment committee and who read the file with no memory of the context that made the first version persuasive. Co-investors conducting parallel diligence — because DFI-backed rounds are rarely single-source — read the same documentation with different underwriting questions in mind, and a document optimized to answer one investor’s concerns can fail a second investor’s concerns silently, with no single visible moment where the gap becomes apparent. Board members who joined at close, sometimes as a condition of the raise itself, start asking in the second or third quarter why the numbers in this reporting cycle don’t reconcile cleanly with the narrative told in the original raise materials. And eventually, whether at eighteen months or three years out, a follow-on round, a strategic equity partner, or an acquirer’s own diligence team will read the institutional file cold — without the founder relationship, the in-person context, or the accumulated goodwill that carried the first raise across the finish line.
The institutional case, in other words, does not get read once by one sympathetic audience and then retired. It gets read repeatedly, by a widening circle of readers, over a period of years, and each new reader arrives with a different question and none of the patience that comes from having been present for the original conversation.
The failure pattern that follows from this is rarely dishonesty, and it is almost never a single dramatic misstatement that someone can point to and call the cause. It is drift — small, individually reasonable decisions that accumulate into a document no longer built for the audience currently reading it.
A positioning narrative built for one specific reader — a DFI investment officer evaluating first-loss risk tolerance and development-impact metrics — gets reused with only cosmetic changes for a commercial co-investor evaluating return profile, or for a board member evaluating governance exposure, or for an auditor evaluating compliance against a regulatory framework that has itself moved since the document was drafted. Each of these readers is looking for something structurally different inside the same paragraph, and a narrative calibrated for the first reader can fail the other three without anyone noticing until someone with real authority over the next tranche of money asks the specific question the document was never built to answer.
Financial reporting tends to evolve in something close to real time, because funders require it to and because the organization itself needs current numbers to run. The governance narrative sitting underneath those numbers — the account of who decided what, on what authority, and why — usually does not receive the same continuous attention. It stays frozen at whatever version was true on closing day, even as the organization it purports to describe has since restructured its reporting lines, brought on new board members, or absorbed a second and third tranche of capital that changed its actual risk profile.
And scale itself, which every one of these organizations is actively pursuing, becomes a liability the original case was never built to survive. A governance and positioning narrative that was coherent and easy to verify at eight mini-grid sites and a single funder relationship becomes considerably harder to hold together at forty sites, three co-investors with different reporting requirements, an expanded board that includes independent members with their own fiduciary obligations, and a regulator that has changed the rules the organization is meant to be complying with. The institutional case does not get rebuilt at each of these thresholds as the organization crosses them. It gets stretched instead, quietly, until the stretching itself becomes visible to someone who has both the authority and the incentive to ask why.
There is a second, quieter version of this same failure that shows up even before any of that scrutiny arrives: organizations that have not yet closed a round but are actively preparing to, and who are building their documentation reactively, in response to whatever the current prospective funder is asking for, rather than building an institutional case robust enough to survive being read by the second and third funder who will eventually ask harder questions. The instinct to treat institutional documentation as something produced on demand, for the audience directly in front of you, is the same instinct that produces the drift described above — it simply produces it earlier, before the first close, instead of after it.
A related but distinct failure sits in register rather than content. Documentation built to persuade — to win a first meeting, to survive an initial screening call, to make the strongest possible case for why this raise should happen — is written in a fundamentally different voice than documentation built to withstand ongoing verification. Persuasive register foregrounds the strongest version of every fact and moves quickly past ambiguity. Verification register does the opposite: it anticipates the specific question a skeptical reader will ask next and answers it before being asked, even where the honest answer complicates the narrative. Most institutional cases are written entirely in the first register, because that is the register that gets a raise closed, and they stay in that register afterward because nobody deliberately decided to change it. A funder’s compliance officer reading a persuasively-written document eighteen months into a covenant relationship is not reading it as a pitch. They are reading it as a record, and a record that reads like a pitch — however honest its underlying content — signals something to a trained reader that the organization did not intend to signal.
None of this tends to announce itself as a single identifiable failure with a clear cause. It shows up instead as friction that gets misdiagnosed. A diligence process that should reasonably take three weeks stretches to nine, and the delay gets attributed to the market being cautious this cycle. A board question that should produce a two-page supporting document instead produces a defensive verbal explanation, and the moment passes without anyone naming what actually happened. A follow-on conversation that seemed promising at the first meeting quietly goes quiet, and the read internally is that the investor lost interest, rather than that the investor’s own internal reviewers couldn’t reconcile what they were told with what they read in the file.
By the time this pattern becomes visible enough to name, it usually gets a name that has nothing to do with its actual cause. “Investors are just slow this cycle.” “We’re between processes right now.” “That board member always asks difficult questions.” Each of these explanations is plausible enough to be accepted, and each of them quietly protects the actual structural problem from ever being examined directly.
The pattern is also asymmetric in a way that rewards early attention. Repairing a governance narrative or a positioning document before a specific reader has flagged it as inadequate is a controlled, unhurried piece of work. Repairing the same document after a co-investor has already noticed the inconsistency, or after a board member has already asked the uncomfortable question out loud, happens under observation, on someone else’s timeline, with the organization’s credibility already partly spent on the exchange. The document is the same either way. The circumstances under which it gets fixed are not, and the second set of circumstances is considerably more expensive than the first — not necessarily in fees, but in the harder currency of institutional trust.
The institutional case is not a document that gets produced once, at the specific moment capital was needed, and then filed. It is a structure that has to continue holding under a particular and recurring kind of examination — conducted by people who were not present when the story was first told convincingly, who have no personal stake in extending the founder the benefit of the doubt the original funder extended, and who are, in most cases, simply doing their job by asking whether the document in front of them still matches the organization it claims to describe.
The capital closing is not the end of that scrutiny arriving. It is the first time the case was tested under real conditions. For every organization sitting inside this current wave of financing, it will be tested again — by a co-investor before the ink is fully dry, by a board member inside the first year, and eventually by someone who was never in the room at all.
— —